The question who pays injury treatment is often more urgent than the injury itself. You may need a doctor, scans, medication, physiotherapy, or time away from work, yet feel unsure whether you will be left with the bill. The answer depends on how the injury happened, what insurance applies, and whether the right claim and medical documentation are in place.
Getting medical care promptly should not wait for every administrative detail to be resolved. Early assessment protects your health and creates a clear clinical record of the injury, symptoms, treatment needs, and capacity for work. That record can be central to the progress of a workers compensation, motor vehicle, or liability claim.
Who pays injury treatment after an accident?
In many cases, the insurer connected to the accident is responsible for reasonable and necessary treatment. That does not always mean payment is automatic on the day of your appointment. A claim may need to be lodged, accepted, or approved before an insurer pays for particular services.
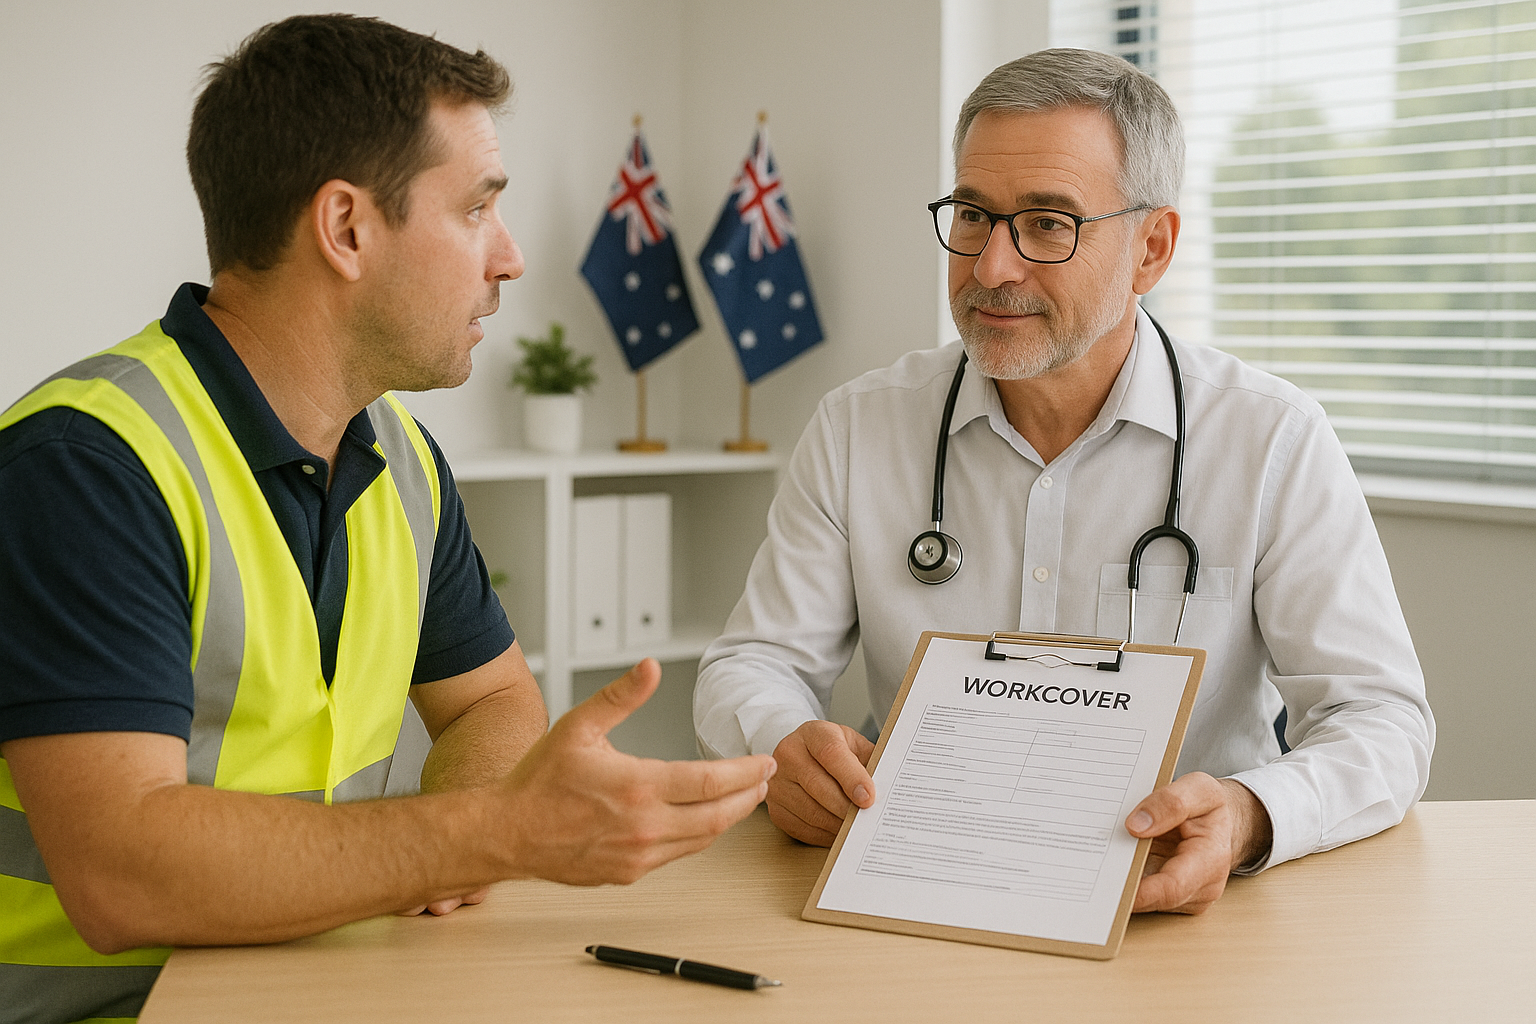
For a workplace injury, workers compensation insurance is usually the first place to look. In New South Wales, this is commonly referred to as a WorkCover claim. If your injury arose out of, or during, your employment, the insurer may cover medical consultations, treatment, rehabilitation, medication, and related services that are reasonably necessary for recovery.
If you were injured in a motor vehicle accident, Compulsory Third Party insurance, often called CTP insurance, may fund treatment. The available support can depend on the circumstances of the crash, the vehicle involved, fault provisions, and the type of claim being made. A medical assessment and accurate certificate can help establish the treatment you require and the connection between the accident and your symptoms.
For an injury in a shop, rental property, public space, or private venue, payment may be pursued through a public or private liability claim. These matters can take longer because the responsible party or its insurer may investigate whether negligence caused the injury. In the meantime, your own health insurance, a treating provider’s billing arrangement, or legal advice may affect how treatment is funded.
The difference between treatment approval and payment
A common source of stress is assuming that an insurer’s responsibility means every provider can immediately send bills to the insurer. In practice, treatment funding has steps. The insurer needs enough information to identify the claim, assess liability where required, and decide whether the proposed treatment is reasonable and necessary.
For a valid workers compensation claim, the process may begin with an employer report, a claim number, and a certificate of capacity from your treating doctor. Once the claim is accepted, approved providers may be able to invoice the insurer directly. This can reduce or remove out-of-pocket costs for covered care.
Some treatment can be approved quickly, while other services may require a referral, treatment plan, quotation, or insurer pre-approval. This is particularly common for extended allied health treatment, surgery, specialist consultations, expensive equipment, or services that continue over a longer period. Approval requirements should not be interpreted as a judgment on your pain. They are part of the claim process, and clear medical evidence helps move it forward.
If a claim is disputed or delayed, ask before assuming a service will be covered. You may still choose to proceed with treatment, but it is wise to understand whether you will need to pay upfront and whether reimbursement is possible later. Keep invoices, receipts, referrals, medical certificates, and correspondence in one place.
Workplace injuries: what workers compensation may cover
Workers compensation generally focuses on treatment that helps you recover from a work-related injury and, where possible, safely return to work. Coverage may include a general practitioner or injury-care consultation, specialist assessments, diagnostic imaging, prescription medication, physiotherapy, chiropractic care, occupational therapy, psychological care, and workplace rehabilitation.
Coverage is not unlimited. The insurer may ask whether the treatment is clinically appropriate, related to the workplace injury, and likely to assist recovery. Pre-existing conditions can also complicate matters. A pre-existing condition does not necessarily prevent a claim, especially where work aggravated it, but the medical records need to explain what changed and why treatment is required now.
Your doctor’s role goes beyond writing a certificate. A thorough assessment records your diagnosis, functional restrictions, treatment plan, and capacity for work. It can also identify when modified duties may be appropriate or when you are not medically fit to return. Accurate documentation gives your employer, insurer, lawyer, and rehabilitation team a consistent basis for decisions.
Workcover.Hills Doctor provides fast, friendly and professional care for injured people who need both clinical treatment coordination and claims-focused medical documentation. For valid WorkCover claims, eligible treatment may be billed without out-of-pocket costs, subject to claim status and applicable approval requirements.
Motor vehicle and public liability claims need clear evidence
With CTP and liability claims, insurers commonly require more detail before they fund ongoing treatment. They may need confirmation of the accident date, mechanism of injury, symptoms, examination findings, diagnosis, and why each recommended service is medically necessary.
This is why it helps to see a clinician experienced in injury care early. A vague note such as “back pain after accident” may not fully explain your limitations or the treatment you need. A clinically accurate report can document the relevant history, objective findings where present, functional impact, referrals, and expected review period without overstating the injury.
If you have a lawyer or case manager, they may request a medico-legal report in addition to your ordinary treatment records. These are different documents with different purposes. Your treating records support ongoing care; a medico-legal report provides an independent, legally compliant opinion for a claim or dispute. Ask which document is needed so the right assessment can be arranged without delay.
What to do when you are worried about the cost
Start by reporting the incident as soon as practical. For work injuries, tell your employer and ask for the insurer and claim contact details. For road accidents, record the vehicle and driver information where possible and report the incident through the appropriate channel. For injuries in public or private places, take photographs if safe to do so, identify witnesses, and report the incident to the property owner or manager.
Next, book a medical assessment. Tell the clinic how the injury occurred, what body parts are affected, what work or daily tasks you cannot manage, and whether you already have a claim number. Bring any incident reports, insurer letters, previous imaging, medication list, and employer paperwork. Details that may feel minor, such as a new sleep problem, driving difficulty, or inability to lift your child, can be clinically relevant.
Before commencing a new course of treatment, ask three direct questions: Is this service approved? Will the provider bill the insurer directly? If not, what will I need to pay and can it be reimbursed? Clear answers can prevent unexpected bills and help you make informed decisions about your care.
When an insurer says no
A denied treatment request is not always the end of the matter. The insurer may be seeking more information, disputing whether the treatment relates to the accident, or questioning whether another option should be tried first. Ask for the decision and reasons in writing.
Your treating doctor may be able to provide further clinical information, update a certificate, or explain why a referral is appropriate. Where a claim itself is denied or liability is disputed, legal advice may be appropriate. Do not alter your medical history or minimize symptoms to make a claim easier. Consistent, honest reporting is the strongest foundation for credible medical evidence.
Can I see a doctor before my claim is accepted?
Yes. Prompt care is often appropriate, particularly when you are in pain, your condition is worsening, or you need advice about work capacity. Payment arrangements vary, so tell the clinic that the injury is claim-related and ask what documentation is needed.
Does workers compensation pay for every treatment I want?
Not necessarily. The treatment generally needs to be reasonable, necessary, and connected to the work injury. Some services require prior insurer approval, especially if they are costly, prolonged, or outside the usual treatment pathway.
What if my employer says the injury was not work-related?
You should still seek medical advice, report the injury, and provide a clear account of what happened. Your employer’s view is relevant, but the insurer and available medical evidence will also matter. Keep copies of all forms, certificates, and communications.
The right question is not only who will pay the next invoice. It is whether your treatment, capacity, and claim are being documented clearly enough to support recovery every step of the way. Early care and accurate records give you the best chance of receiving the help you need without carrying the process alone.